Food delivery has changed the small farm business model by adding a new set of intermediaries between the farm gate and the customer. A direct-market grower who once sold at a stand, through a CSA, or to a neighborhood restaurant now competes for buyers who start their search with the phrase "food delivery near me" — and that search usually ends on a platform, not at the farm's own page.
The shift is less about agronomy than about channel economics. Delivery platforms charge fees, control the customer relationship, and set the terms of how a seller appears. Growers who understand those terms can decide when a platform channel pays and when a farm's own sales channels still do the job better.
Why does "food delivery near me" matter to a farm seller?
Because that phrase is where the customer journey now begins. Consumers searching for food near them rarely distinguish between a restaurant, a specialty grocer, and a farm's web store. They see whatever a platform or map result surfaces first. If a farm's products are not in that result set, the farm is invisible to that buyer, no matter how good the produce is. We covered a connected angle in What a food recall actually costs the industry.
That visibility problem is structural. When food writers profile a dining scene, they now routinely note which venues offer delivery. In its roundup of the best new restaurants in Queens, Eater NY attaches an "Order delivery from Grubhub" line to nearly every listing — from a takeout counter in Astoria to a Cantonese banquet hall in Long Island City. Delivery availability has become a standard field in how food businesses are described and found.
For a small farm, the lesson is uncomfortable but useful: the platforms have become part of the storefront, even for businesses that never asked for that role.
What do third-party delivery platforms actually cost a seller?
Platforms generally charge sellers a commission on each order, and those commissions are typically a percentage of the order total rather than a flat fee. The exact rates vary by platform, market, and program tier, and platforms publish them in their own merchant agreements — which means a grower should read the current terms for their own market rather than rely on any general figure. What does not vary is the structure: the fee comes off the top of every order, before the farm's own margin is calculated.
There are less obvious costs too. The platform, not the farm, owns the customer data in most arrangements, so repeat buyers may never appear in the farm's own list. Menu and product presentation follow the platform's templates. And pricing control is often constrained, because platforms commonly require that prices listed on the app match or relate to in-store prices.
None of this makes platforms a bad deal in every case. It makes them a channel with specific terms that need to be priced into the farm's own cost of selling.
How do ghost kitchens fit into the picture?
A ghost kitchen is a shared commercial cooking space that hosts delivery-only food businesses, usually with no storefront of its own. The model exists because delivery demand made rent for a visible retail location optional for some sellers. In its Queens coverage, Eater NY documented the model in practice: a D.C.-based takeout chain opened inside the Sunnyside Eats ghost kitchen, serving customers with no dining room at all.
For farm sellers, ghost kitchens point to a related idea rather than a direct option. A farm that sells prepared products — salsas, sauces, baked goods, value-added items — can look at shared commercial kitchen space as a way to reach delivery customers without building a retail site. The economics still need to work: shared-kitchen rent, platform commissions, and packaging all stack. But the infrastructure now exists in many metro areas, and that is a real change from a decade ago.
What are the practical paths for a direct-market grower?
The channel decision comes down to matching each sales route to its actual cost and its actual customer. The main options:
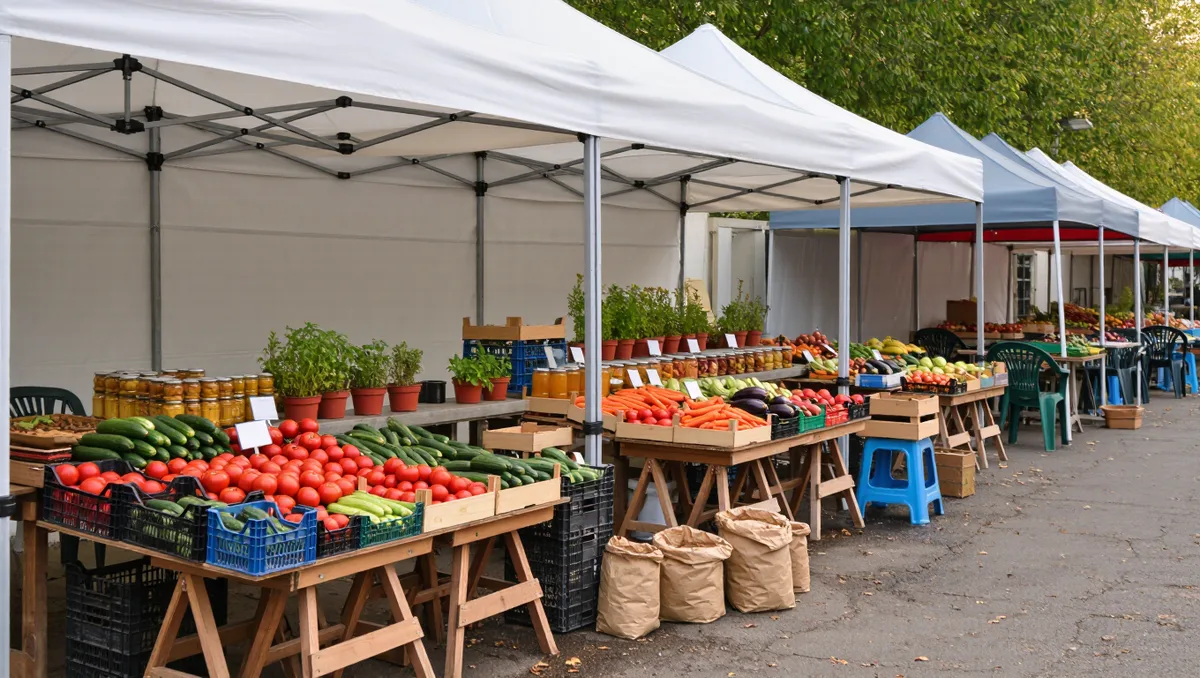
- Farm's own online store with local delivery or pickup. The farm keeps the customer data and the full margin, and pays only its own delivery cost. The trade-off is that the farm must generate its own demand, since no platform is sending orders.
- Third-party platform listing. The platform brings discovery — the "near me" traffic — but takes a commission and controls the relationship. This can make sense for high-margin prepared products and less sense for low-margin commodity produce.
- Wholesale to restaurants that deliver. The farm sells to a food business that has already absorbed the platform fees. The restaurant relationship is the farm's own, and the platform economics are someone else's problem. Food media's restaurant coverage, such as Time Out New York's guide to Queens dining, shows how heavily restaurants now lean on delivery and takeout as a revenue line — which shapes what they can pay their suppliers.
- CSA and farmers market channels. These keep the highest share of the food dollar on the farm, as our earlier piece on why farmers get 12 cents of every food dollar explains. Their limit is geographic reach and season length.
Our analysis: the growers best positioned here treat platforms as one paid acquisition channel among several, not as the whole business. The platform buys visibility; the farm's own channels keep the customer.
What should a grower check before signing with a platform?
Read the merchant agreement the way you would read a seed contract. The items that move the math most:
- The commission schedule — what percentage comes off each order, and whether delivery, marketing, and payment processing are billed separately.
- Price parity rules — whether the platform restricts what you can charge on the app versus elsewhere.
- Who owns the customer — whether the farm learns who bought, or the platform keeps that data.
- Product fit — delicate greens and mixed CSAs often survive delivery poorly; shelf-stable and frozen value-added items travel well. Cold-chain handling is a shared responsibility, and food safety obligations do not disappear because a third party carried the box — a point our coverage of what a food recall actually costs makes in detail.
Ask for the terms in writing, run the numbers on a realistic week of orders, and treat the first season on any platform as a trial with a defined end date.
Where the model goes from here
Delivery is now part of the local food infrastructure, the way a farmers market pavilion or a wholesale terminal once was. The evidence from the restaurant side — delivery links standard in listings, ghost kitchens hosting storefront-less brands — shows the demand is real and the intermediaries are entrenched. The small farm's opportunity is not to beat the platforms at their own game. It is to use them deliberately, price their fees honestly, and keep building the direct channels where the farm keeps both the margin and the relationship.